

Risk Management · 2025
In this section3 topics
Risk Management Policy & Plan
Policy & Plan Description
Risk management is the cornerstone of stable and sustainable growth. The Bank is committed to developing a comprehensive risk management system that covers all key areas, operating in accordance with the Bank of Thailand's regulatory guidelines. We are prepared to address challenges regarding credit quality and uncontrollable external factors through effective strategic planning and an appropriate organizational structure.
The Bank has established the Risk Oversight Committee and the Risk Management Committee to provide holistic supervision of risk management processes. Our framework is rooted in good corporate governance, featuring robust reporting systems, monitoring tools, and clear control procedures. Furthermore, the Bank fosters a risk-aware culture across all levels of staff, ensuring a deep understanding of practices and responsibilities through risk management policies, specialized training programs, and departmental supervision.
The organizational structure is designed to ensure a balance of power and operational efficiency. This enables the Bank to manage risks appropriately, supporting long-term growth and building confidence among all stakeholders.
Risk Governance Structure
Organizational structuring is a fundamental principle employed by the Bank for risk management. The Bank has established a hierarchy of Board of Directors, Sub-Committees, and supporting functions (the Second Line of Defense) to enhance operational efficiency. This structure facilitates effective risk management aligned with our business goals of driving continuous growth and generating stable, long-term returns, as detailed below:
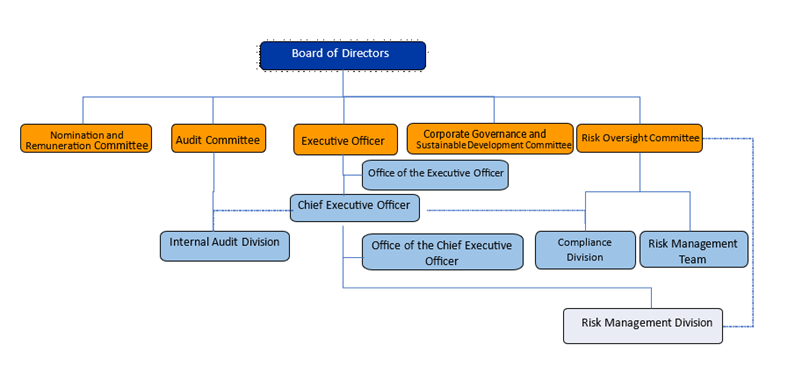
The Risk Oversight Committee is a sub-committee directly responsible for overseeing various aspects of risk management and reporting to the Board of Directors. Its mandate includes defining Risk Tolerance levels for Key Risk Indicators (KRIs) and establishing appropriate action plans for risks reaching the warning level (Yellow Zone) and caution level (Red Zone), ensuring alignment with external conditions and the Bank’s future growth strategies.
The Risk Management department serves as the primary unit for monitoring and analyzing risk fluctuations. It develops comprehensive monthly Dashboards covering multiple dimensions, such as credit growth and concentration, asset quality, provision adequacy, money market and interest rate conditions, and liquidity. These reports empower operational units to make informed strategic decisions within the approved risk appetite. Furthermore, the Risk Management Group presents monthly risk analysis summaries to the Risk Oversight Committee and the Board of Directors to ensure effective and prudent risk governance.
In addition, the Internal Audit, under the oversight of the Audit Committee, is responsible for reviewing the effectiveness and adequacy of the risk management framework, internal control systems, and operational processes, ensuring full compliance with professional standards and relevant regulatory requirements.
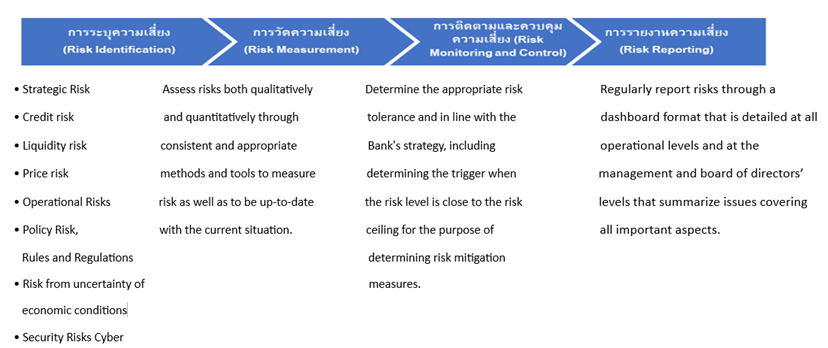
The Bank's risk management framework, policies, and guidelines were comprehensively reviewed in 2025 and approved by the Board of Directors at Meeting No. 10/2025 on October 21, 2025. The core risk management processes are summarized as follows:
Risks to the Company's Business Operations
Risk Register
| Risk Name | Risk Characteristics | Consequences | Management Measures | Related Risk Factors |
|---|---|---|---|---|
| Strategic Risk | Strategic risk arises from decisions or actions undertaken by the Bank that are inconsistent with changes in the business environment, economic conditions, technology or innovation, and rapidly evolving regulations, or from the inability to adjust its operating strategies in response to such changes, which may adversely affect the Bank’s competitiveness and its ability to generate sustainable long-term returns. | Strategic risk may affect the Bank in both the short and long term. In the short term, the Bank may experience a decline in operating performance resulting from strategic decisions that are not aligned with market conditions, as well as increased costs arising from investments in projects or technologies that fail to generate the expected returns. In addition, delays in adapting to change or the implementation of strategies that do not adequately address customer needs may lead to a decline in customer and investor confidence, thereby affecting the Bank’s image and credibility in the near term. In the long term, strategic risk may cause the Bank to lose its competitiveness if it is unable to adapt in a timely manner to technological changes and evolving consumer behavior. Such impacts may undermine the sustainability of the business, limiting the Bank’s ability to sustain growth and generate stable returns. This may also adversely affect the Bank’s image and brand over time, with implications for capital raising and relationships with stakeholders. Furthermore, if the Bank’s strategies are not aligned with new laws, regulations, or regulatory requirements, the Bank may be subject to penalties or incur significant costs in adjusting its operations to achieve compliance, which could adversely affect its financial stability and organizational credibility in the future. | The Bank implements prudent measures to manage strategic risk by emphasizing the establishment of continuous monitoring and review processes for relevant risk factors, enabling timely adaptation to changes in the business environment. Key measures include defining a strategic framework aligned with the Bank’s vision and long-term objectives, as well as conducting regular strategy review meetings to assess the appropriateness of business plans and operational approaches in the context of evolving economic conditions, technological developments, and regulatory changes. In addition, the Bank monitors external risk factors, such as economic trends, interest rates, market competition, and technological advancements, as well as internal risk factors, including operational efficiency and workforce readiness, in order to adjust its strategies appropriately and mitigate potential impacts. Regular reporting is also made to the Board of Directors and senior management to ensure that strategic decisions are undertaken prudently and remain consistent with the Bank’s risk appetite. | 728 · Description: Volatility in the industry in which the company operates · Info category: STRATEGIC_RISK · 729 · Description: Behavior or needs of customers / consumers · Info category: STRATEGIC_RISK · 730 · Description: Government policy · Info category: STRATEGIC_RISK · 1715 · Description: Economic risk · Info category: STRATEGIC_RISK |
| Credit Risk | Credit risk is one of the Bank’s most significant risks. It refers to the risk that customers or counterparties are unable to comply with the terms and conditions stipulated in contractual agreements, including instances where borrowers default on partial or full repayment obligations, as well as a decline in the value of collateral during the loan tenor. | If the Bank is unable to effectively manage credit risk, or if such risk management is conducted inappropriately, non-performing loans (Non-Performing Loans: NPLs) may increase, requiring the Bank to set aside higher expected credit loss provisions. This would result in increased reserve costs and adversely affect the Bank’s overall operating performance and profitability. Credit risk impacts not only asset quality and financial performance but also the Bank’s capital adequacy level, which must be maintained in accordance with regulatory requirements. Regulators require the Bank to maintain capital commensurate with its Risk-Weighted Assets (RWA). A deterioration in asset quality due to an increase in NPLs would lead to higher risk-weighted assets, thereby requiring the Bank to hold a higher level of capital to comply with prudential capital requirements. Such impacts may constrain the Bank’s ability to expand its business and sustain growth, as additional capital would need to be allocated to support the increased risk exposure. If the Bank is unable to raise capital as required, it may need to reduce its risk-weighted assets, for example by slowing new loan disbursements or restructuring its loan portfolio to maintain capital adequacy at an appropriate level. This, in turn, could adversely affect the Bank’s competitive position and its ability to generate sustainable long-term returns. | The Bank manages credit risk by maintaining an appropriate balance between loan growth and risk exposure within its acceptable risk appetite, through a comprehensive risk management process covering all stages of the lending cycle. This begins with the establishment of an organizational structure incorporating appropriate checks and balances, together with clearly defined credit approval authority levels aligned with risk levels (risk-based authority), to ensure prudent and transparent decision-making. The Bank has established credit underwriting criteria under product program frameworks, which encompass borrower qualifications, interest rates, credit limits, collateral requirements, and other relevant factors, serving as standardized guidelines for product offerings to customers. Such product programs are assessed with respect to risk considerations and appropriate risk-adjusted returns, and must be reviewed by relevant functions before being proposed to the Executive Committee for approval. In the credit analysis process, the Bank assesses potential risks arising from transactions with customers and establishes appropriate risk mitigation measures, such as determining suitable loan types and credit limits, as well as requiring adequate collateral. The Bank also places importance on enhancing the knowledge and capabilities of its Relationship Managers and Credit Advisors by providing training to strengthen their preliminary customer assessment skills, as these personnel maintain the closest contact with customers. The Bank maintains a clear collateral acceptance policy, taking into account the type of asset, its liquidity, and valuation in order to determine an appropriate loan-to-value ratio. Collateral valuation is conducted by external appraisers, and property inspections are carried out prior to loan approval. For certain higher-risk customers, the Bank may require a credit guarantee from the Thai Credit Guarantee Corporation to mitigate potential losses in the event of default. In addition, the Bank emphasizes the management of concentration risk by setting maximum exposure limits for large borrowers or connected customer groups and by diversifying its loan portfolio across various industries to reduce the impact of excessive volatility in any particular sector. Nevertheless, the Bank continues to place strong emphasis on closely monitoring credit risk and responding promptly to evolving circumstances. It has established systems to continuously monitor loan quality and customers’ repayment behavior in order to identify early warning signs of potential deterioration and to implement corrective actions or adjust strategies in a timely manner. The Bank also monitors external factors, such as economic conditions, interest rates, and industry trends, to assess their potential impact on asset quality and customers’ debt servicing capacity. The Bank has developed and implemented various risk management tools to enhance the effectiveness of credit risk management, including data analytics systems and credit risk models capable of estimating the probability of default. It also utilizes Key Risk Indicators (KRIs) to monitor and provide early warning signals of emerging risks. These tools are regularly reviewed and refined to ensure alignment with changing business environments and international risk management standards. In addition, the Bank conducts credit risk stress tests under various hypothetical scenarios to assess the impact on the adequacy of loan loss provisions and to support capital planning, ensuring sufficient capital to effectively sustain the Bank’s operations. | 763 · Description: Default on payment or exchange of goods · Info category: FINANCIAL_RISK |
| Liquidity Risk | Liquidity risk refers to the risk that the Bank is unable to meet its payment obligations as they fall due, which may result from an inability to obtain sufficient funding or cash flows in a timely manner, or from the ability to obtain funding only at costs exceeding the Bank’s acceptable thresholds. Such circumstances may not only affect the Bank’s short-term operational capability but could also have longer-term implications for its earnings, financial stability, and capital position. Deposits constitute the Bank’s primary source of funding; therefore, the Bank’s ability to mobilize deposits is a key determinant of its liquidity risk profile. Several factors influence deposit mobilization, including the level of competition in the financial market, interest rate trends, depositor confidence in the Bank’s financial soundness, the diversity of deposit products to meet customer needs, accessibility of services through branch and digital channels, and the overall quality of customer service. Liquidity risk is also affected by external factors, such as volatility in financial markets, economic uncertainty, and events that may undermine depositor confidence. If the Bank is unable to manage liquidity effectively, it may need to rely on short-term funding sources in the financial markets, which typically carry higher costs and may adversely affect profitability and long-term capital stability. | Liquidity risk is a critical factor affecting the Bank’s stability and ability to operate effectively. If the Bank is unable to secure sufficient funding or cash flows to meet its obligations as they fall due, it may face multidimensional impacts in both the short and long term. In the short term, the Bank may need to rely on short-term funding sources from the financial markets, which typically carry higher costs, thereby increasing funding expenses and adversely affecting operating performance. In addition, liquidity constraints may limit the Bank’s ability to respond promptly to customer needs, potentially undermining customer confidence and the Bank’s reputation. In the long term, inadequately managed liquidity risk may affect the Bank’s capital position, as higher funding costs could reduce profitability. If such conditions persist, the Bank may need to scale back asset growth or postpone investments in order to maintain liquidity at prudent levels, which could constrain business expansion and growth potential. Furthermore, liquidity risk may impair the Bank’s credibility in the eyes of depositors, investors, and regulators, potentially leading to challenges in future fundraising efforts. These potential impacts underscore the importance of prudent and proactive liquidity management to ensure that the Bank can maintain financial stability and sustain stakeholder confidence under all market conditions. | Overall, the Bank’s liquidity remains at a high level and is sufficient to support its business operations. This reflects its strong deposit mobilization capability, as evidenced by a high level of deposits per branch and a stable deposit base, supported by a consistently high deposit rollover rate. In addition, the Bank has the capacity to access alternative funding sources from reputable global financial institutions. The Bank has been assigned a National Long-Term Rating of ‘A(tha)’ and a National Short-Term Rating of ‘F1(tha)’, with a “Stable” outlook, by Fitch Ratings (Thailand), affirming its financial strength and credibility and reinforcing confidence among depositors and stakeholders. In managing liquidity risk, the Bank complies with regulatory requirements to maintain liquid assets at levels not lower than recognized prudential standards. It also adopts an investment policy focused on high-quality, liquid assets with appropriate risk diversification to preserve financial stability under all market conditions. The Bank has implemented liquidity early warning systems through risk indicators to provide timely signals for management to monitor and control liquidity risk effectively. In addition, contingency funding plans have been established to address both general liquidity stress scenarios and unexpected liquidity events without prior warning. The Bank further manages liquidity by maintaining holdings of high-quality liquid assets, including deposits with the Bank of Thailand and commercial banks, engaging in private repurchase agreement (Private Repo) transactions, participating in money market lending and borrowing activities, and investing in government and state enterprise debt securities. These measures ensure that the Bank’s liquidity position remains at a prudent level and is resilient to market volatility. | 761 · Description: Insufficient sources of funding · Info category: FINANCIAL_RISK · 762 · Description: Change in financial and investment policies of financial institutions that affect business operations · Info category: FINANCIAL_RISK · 763 · Description: Default on payment or exchange of goods · Info category: FINANCIAL_RISK · 764 · Description: Fluctuation in exchange rates, interest rates, or the inflation rate · Info category: FINANCIAL_RISK · 1724 · Description: Liquidity risk · Info category: FINANCIAL_RISK |
| Market Risk | Market risk refers to the risk arising from changes in the value of the Bank’s assets, liabilities, and off-balance sheet obligations, which may adversely affect its earnings and financial stability. Key factors contributing to this risk include mismatches in reference interest rates between the Bank’s primary assets such as loans to customers and its major liabilities such as deposits as well as interbank transactions and money market activities. Such mismatches may result in an interest rate gap, which can affect the Bank’s net interest income and profitability in both the short and long term | Market risk directly affects the Bank’s income, profitability, and cash flows, as changes in interest rates and financial instrument prices can create significant volatility in operating results. Movements in interest rates are influenced by various macroeconomic factors, including policy rates, macroeconomic trends, inflation levels, and the monetary policies of the Bank of Thailand and other central banks. Such changes may alter the Bank’s funding cost structure and net interest income. In addition, market risk may arise from fluctuations in the prices of instruments in the money and capital markets in which the Bank invests as part of its liquidity risk management. The prices of these instruments are driven by market supply and demand dynamics, as well as external factors such as global economic conditions, interest rate volatility, and investor sentiment. Adverse price movements may reduce the value of the Bank’s investments, thereby affecting overall profitability and financial stability. | The Bank manages market risk by focusing on aligning the maturities of loans and deposits to minimize the risk arising from interest rate mismatches. In addition, the Bank prepares a Repricing Gap report to closely monitor interest rate trends and customer behavior. It also assesses Net Interest Income (NII) sensitivity over the next 12 months to ensure stable net interest income and to effectively manage exposure to market volatility. With respect to investments, the Bank emphasizes investments in assets with high stability and liquidity, with the majority of its portfolio comprising government and state enterprise debt securities, as well as deposits with the Bank of Thailand and commercial banks, in order to preserve capital security and maintain liquidity readiness; in managing risks arising from changes in market prices of financial instruments, the Bank maintains strict oversight through the Asset and Liability Management Committee (ALCO) and the Risk Management Committee to ensure that its operations remain within the Bank’s acceptable risk appetite and are aligned with prevailing market conditions. | 765 · Description: Fluctuation in return on assets or investment · Info category: FINANCIAL_RISK |
| Operation Risk | Operational risk refers to the risk of loss resulting from inadequate or failed internal processes, personnel, systems, or information technology, as well as from external events beyond the Bank’s control, such as natural disasters, political events, or other emergency situations, and it also encompasses legal and regulatory compliance risks, including the risk of lawsuits or legal proceedings, regulatory fines or penalties imposed by authorities, as well as losses arising from out-of-court settlements and similar circumstances | Operational risk may affect the continuity of the Bank’s operations and its ability to deliver services. It may result in financial impact, including loss of income or the incurrence of additional expenses, thereby affecting operating performance and the Bank’s capital position. It may also have a customer impact by impairing service quality and reducing customer confidence, as well as a reputation impact that could adversely affect the Bank’s standing and credibility. Accordingly, operational risk is a key risk that the Bank manages, monitors, and controls closely in order to prevent and mitigate potential losses. Effective operational risk management also enhances operational efficiency, improves service quality, and strengthens customer confidence. | Operational risk management is conducted under the highest level of oversight by the Bank’s Board of Directors, which approves the operational risk management policy to serve as a framework for all departments in managing risk. The Board has delegated authority to the Risk Management Committee to identify, assess, monitor, and manage the Bank’s operational risks, ensuring that risk management activities are carried out appropriately and comprehensively by responsible parties. The Operational Risk Management function is responsible for overseeing and managing operational risk on a bank-wide basis. In managing operational risk, the Bank places importance on risks arising from both internal and external factors, including those beyond its control, to prevent adverse impacts on its business operations and customer services. The Bank undertakes the following measures:
In addition, the Bank manages risks arising from the adoption of technology to enhance the efficiency of financial services provided to customers and the development of digital service platforms. An enterprise-wide IT risk appetite has been established to facilitate the monitoring and effective management of key technology-related risks. | 758 · Description: Violations of laws and regulations · Info category: COMPLIANCE_RISK · 741 · Description: Systems or internal control system · Info category: OPERATIONAL_RISK · 742 · Description: Human error in business operations · Info category: OPERATIONAL_RISK · 1723 · Description: Legal risk · Info category: COMPLIANCE_RISK · 750 · Description: Climate change and disasters · Info category: OPERATIONAL_RISK |
| Compliance Risk | Compliance risk refers to the risk arising from the Bank’s failure to comply fully with applicable laws, regulations, rules, standards, and guidelines governing its business activities and transactions, including the Financial Institutions Business Act, the Securities and Exchange Act, the Anti-Money Laundering Act, the Personal Data Protection Act, as well as notifications and directives issued by relevant regulatory authorities, and such non-compliance may result in financial losses, reputational damage, regulatory intervention, or penalties imposed by supervisory authorities, thereby adversely affecting stakeholder confidence and the stability of the Bank’s business operations. | Compliance risk may have both financial and reputational impacts on the Bank. Failure to fully comply with applicable laws, regulations, and requirements may result in regulatory sanctions, such as fines, remedial measures, or business restrictions, which could impose additional costs and adversely affect operating performance. Furthermore, such risk may undermine the confidence of depositors, investors, and other stakeholders if regulatory breaches or legal proceedings occur, thereby affecting the Bank’s image and credibility in the long term. These impacts are not limited to the costs of process remediation or the payment of penalties; they may also constrain the Bank’s ability to expand its business and maintain relationships with counterparties and customers. In addition, the Bank may be required to increase investments in internal controls and monitoring systems to prevent recurrence, leading to higher overall operating costs. | The Bank has established a Compliance Business Unit, which has a key role in supporting and overseeing the Bank’s operations to ensure compliance with applicable laws, regulations, and rules. The unit is responsible for providing guidance and advice to internal departments on legal and regulatory requirements, as well as closely monitoring updates and changes in regulations issued by supervisory authorities to enable the Bank to adapt and operate in accordance with applicable requirements. In addition, the Compliance Business Unit is responsible for developing the Bank’s compliance risk management framework, encompassing risk identification and assessment, review of operational processes to ensure adherence to regulatory requirements, and preparation of monitoring reports for regular submission to management and the Risk Management Committee, thereby ensuring that the Bank effectively and transparently controls and manages compliance risk. | 756 · Description: Change in laws and regulations · Info category: COMPLIANCE_RISK · 758 · Description: Violations of laws and regulations · Info category: COMPLIANCE_RISK · 759 · Description: Corporate Governance · Info category: COMPLIANCE_RISK |
| Cyber Risk | Cyber risk refers to the risk arising from unauthorized access to or attacks on information technology systems, which may affect data security, service continuity, and customer confidence. As consumer behavior increasingly shifts toward mobile banking and digital channels, the volume of online transactions continues to grow, leading to heightened exposure to cyber threats such as phishing, malware, and attempts to steal personal data. The expansion of digital services and system integration with business partners has also increased the complexity of the Bank’s technology infrastructure. Without adequate control measures, this may expose the Bank to risks of data breaches, system disruptions, or loss of confidence among customers and stakeholders. Cyber risk is therefore one of the key risks requiring rigorous and continuous management to address evolving consumer behavior and the rapidly changing technological landscape. | Cyber risk may have significant impacts on the Bank’s operations, including financial, reputational, and stakeholder confidence implications. A cyberattack or unauthorized access to information could disrupt service systems, affecting business continuity and customer satisfaction. In addition, a personal data breach represents a high-impact risk, as it may lead to legal proceedings or regulatory penalties under the Personal Data Protection Act (PDPA), thereby imposing direct financial costs and adversely affecting the Bank’s operating results. Such impacts are not limited to remediation expenses and regulatory fines; they also include reputational damage and diminished confidence among customers, investors, and business partners, which may impair the Bank’s competitiveness and long-term growth. Furthermore, the Bank may be required to make additional investments in cybersecurity systems and internal control measures to prevent recurrence, resulting in higher overall operating costs. | The Bank is committed to continuously enhancing information security and strengthening its defenses against cyber threats by developing a stable security infrastructure, implementing proactive system protection measures, and enhancing the knowledge and capabilities of its personnel, which are critical components in safeguarding systems and data against evolving and increasingly sophisticated threats. To ensure effective cyber risk management, the Bank has adopted the Cyber Resilience Management Framework prescribed by the Bank of Thailand, encompassing the following key approaches:
| 732 · Description: Changes in technologies · Info category: STRATEGIC_RISK · 744 · Description: Information security and cyber-attack · Info category: OPERATIONAL_RISK · 1720 · Description: System disruption risk · Info category: OPERATIONAL_RISK |
| Sustainability Risk | Sustainability risk refers to the risk that the Bank may be unable to adapt or conduct its business in alignment with evolving expectations relating to Environmental, Social, and Governance (ESG) factors, which have become increasingly important to stakeholders. This risk may stem from regulatory developments concerning greenhouse gas emission reduction, efficient resource utilization, and compliance with labor and human rights standards. Failure to align operations with these standards may adversely affect investor, customer, and public confidence, and could limit the Bank’s access to sustainable funding sources. In addition, sustainability risk encompasses the impacts of climate change, which may affect asset quality and the debt-servicing capacity of clients in certain industries such as agriculture, energy, and manufacturing. It also includes the risk of failing to meet stakeholder expectations regarding social and environmental responsibility, which may undermine the Bank’s reputation and credibility over the long term. | Sustainability risk may significantly affect the Bank’s operations, financial performance, and reputation, given that its stakeholders include local communities surrounding its branches nationwide, business partners within its supply chain, institutional shareholders with strong sustainability awareness, regulatory authorities overseeing the banking sector, government agencies granting operating licenses, and accounting standard-setters that prescribe sustainability disclosure requirements, all of whom place considerable importance on sustainability matters; accordingly, if the Bank fails to effectively manage sustainability risk, it may face substantial adverse impacts, including financial consequences, deterioration in operating performance, and damage to its reputation and stakeholder confidence. | For further details on sustainability matters, the Bank has prepared a Sustainability Development Report, which is disclosed on the Bank’s website under the Investor Relations section. | 1717 · Description: ESG risk · Info category: STRATEGIC_RISK · 753 · Description: Impact on human rights · Info category: OPERATIONAL_RISK |
| Emerging Risks | Emerging Risks refer to risks that may affect the Bank’s business operations over the next three to five years, with potential implications for its business activities, operational performance, financial position, as well as environmental, social, and governance matters. Based on the Bank’s assessment, key emerging risks include geopolitical risk, volatile financial market risk, rising household debt risk, global economic slowdown risk, government policy risk, and climate change risk. | The six emerging risks described above may adversely affect the Bank’s business operations, liquidity, asset quality, and capital adequacy as follows:
In addition to physical risks, transition risks may arise from the need to adapt to evolving environmental regulations and policies, such as the enforcement of greenhouse gas reduction measures, the shift toward clean energy, and the implementation of more stringent ESG standards, which may increase customers’ operating costs and reduce profitability, thereby exposing the Bank to heightened credit and strategic risks; furthermore, growing stakeholder expectations regarding sustainability place additional pressure on the Bank to adapt promptly, and failure to align operations with such trends may result in a loss of confidence, reduced access to sustainable funding sources, and strategic risks affecting the Bank’s long-term financial stability, competitiveness, and reputation. | The Bank has undertaken the following measures to prepare for and mitigate the potential impacts of emerging risks:
| 730 · Description: Government policy · Info category: STRATEGIC_RISK · 764 · Description: Fluctuation in exchange rates, interest rates, or the inflation rate · Info category: FINANCIAL_RISK · 1715 · Description: Economic risk · Info category: STRATEGIC_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK · 1719 · Description: Climate change and disasters · Info category: STRATEGIC_RISK |
Risks to Securities Holders' Investment
Risk Register
| Risk Name | Risk Characteristics | Consequences | Management Measures | Related Risk Factors |
|---|---|---|---|---|
| Investment risk on security holder | A shareholding structure in which major shareholders hold more than 50% of the total shares may give rise to significant governance risks, as such shareholders possess substantial control over policy decisions and the strategic direction of the organization. This concentration of ownership may affect the balance of governance processes and challenge the independence of the Board of Directors and the Audit Committee. The Bank may also face potential conflicts of interest if decisions are made in a manner that favors business partners, affiliated companies, or related parties of the major shareholders rather than prioritizing the best interests of all stakeholders. The Bank’s major shareholders consist of VNB Holding Co., Ltd., Thai Life Insurance Public Company Limited, and the Chaiyawan Group, collectively holding 70.12% of the total issued shares. As the parent company of the financial group, VNB Holding Co., Ltd. is required to maintain a shareholding of more than 50% in order to retain its status as the parent company of the financial business group. | A shareholding structure with ownership concentrated among major shareholders may pose governance challenges to the Bank, as decision-making authority could become imbalanced and potentially affect the independence of oversight bodies; if undue influence is exercised, the Bank may face risks of related-party transactions or actions inconsistent with good governance principles, potentially leading to intensified regulatory scrutiny and reputational damage, undermining stakeholder confidence, including that of investors and depositors and affecting the Bank’s future fundraising capability; moreover, strategic missteps, inappropriate investment decisions, or asset management practices that favor particular individuals could directly impact financial performance, and therefore the Bank places strong emphasis on transparent oversight mechanisms and robust risk management systems to mitigate potential adverse effects and preserve long-term organizational stability. | The Bank places strong emphasis on systematically managing governance risks associated with a highly concentrated shareholding structure in order to preserve transparency, independence, and the confidence of all stakeholder groups. It has strengthened the role of independent directors to ensure effective oversight and appropriate checks and balances over major shareholders, established an appropriate proportion of independent directors in accordance with regulatory requirements, and assigned independent directors key roles on subcommittees responsible for audit, risk oversight, and nomination and remuneration. The Bank has established a comprehensive Related Party Transactions policy framework, supported by rigorous and transparent approval procedures. Transactions that may give rise to conflicts of interest are subject to review and approval by the Audit Committee. The Bank has also enhanced its monitoring and reporting systems to ensure that such transactions are transparent, traceable, and clearly auditable, including appropriate public disclosure. From a governance perspective, the Bank has strengthened its internal audit processes to enable thorough assessment of risks that may stem from the influence of major shareholders, with direct reporting to the Audit Committee. In addition, regular training and communication on ethics, transparency, and independence are provided to executives and employees throughout the organization. The Bank has also implemented measures to strengthen information governance and disclosure practices to ensure that information provided to stakeholders is complete, accurate, and compliant with the requirements of the Bank of Thailand, the Securities and Exchange Commission Thailand, and the Stock Exchange of Thailand, thereby promoting the highest level of transparency. In addition, the Bank has established whistleblowing channels that enable employees and external parties to report complaints or early warning signals confidentially and anonymously. Through these measures, the Bank mitigates the risk of undue influence by major shareholders, reinforces clear checks and balances, and maintains strong governance standards and long-term sustainability in its business operations. | 768 · Description: Return from investment of securities holder · Info category: HOLDER_RISK · 2969 · Description: Risk of the company having a majority shareholder holding > 50% of shares · Info category: HOLDER_RISK |